Summary
Paying for Independent Living with limited savings is achievable when you explore all available financial resources beyond just what's in the bank. Families often discover that combining multiple funding sources—from home equity to family contributions—creates a more sustainable solution than relying on savings alone.
- Understand what's included in monthly fees (housing, meals, housekeeping, programs) and subtract expenses your parent will no longer have to see the true cost difference
- Explore existing assets like home equity, life insurance cash value, personal property sales, or reverse mortgages that may help fund the move
- Consider family contributions through written agreements or flexible arrangements, with open communication to avoid financial misunderstandings
- Ask communities directly about current pricing, floor plans, included services, additional fees, and any flexible payment options or promotions
- Work with a financial advisor to develop a realistic long-term budget that accounts for monthly income, assets, anticipated rate increases, and unexpected expenses
Navigating how to pay for independent living with limited savings can feel overwhelming, especially when your parent is ready for a simpler lifestyle. Monthly costs may seem out of reach at first, but looking beyond savings can reveal additional financial options.
From existing assets to family contributions, several approaches may help make independent living more affordable. Understanding these resources can help families plan without compromising their long-term financial stability.
Understanding the True Cost of Independent Living
Before exploring funding options, identify what the monthly fee actually includes. Independent living communities often combine several household expenses into one payment, making it easier to compare costs.
Depending on the community, monthly fees may cover:
- Housing and maintenance: Apartment accommodations, property upkeep, and routine repairs.
- Dining services: Chef-prepared meals without the responsibilities of grocery shopping and cooking.
- Housekeeping and transportation: Convenient services that simplify everyday responsibilities.
- Lifestyle programs: Social events, fitness opportunities, and community gatherings.
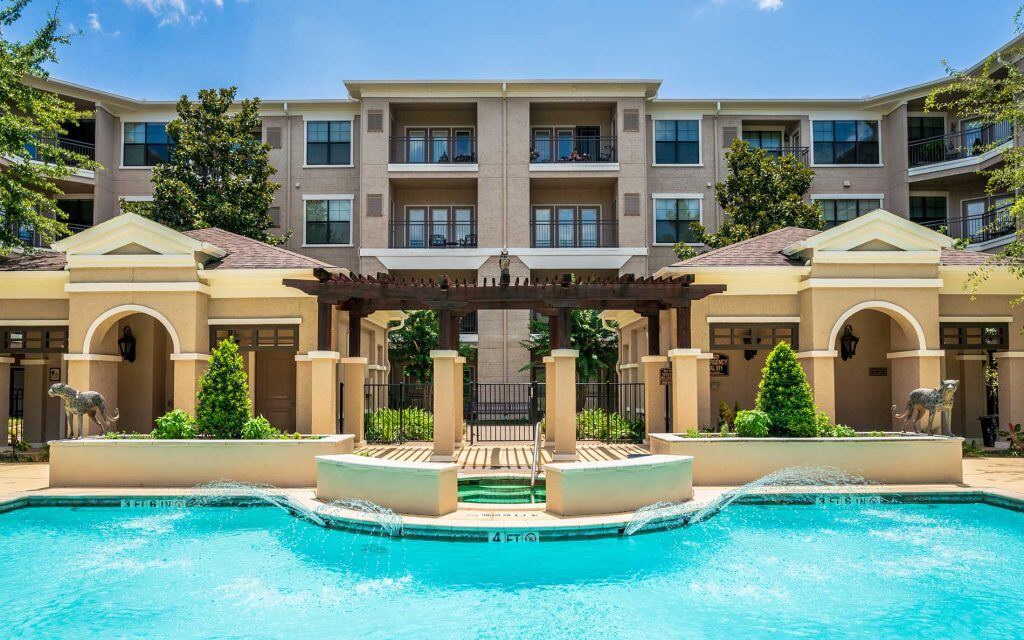
At Conservatory at Champion Forest in Spring, TX, residents enjoy an Active Independent Living community with resort-style amenities, Sensations Dining, and Celebrations events that bring convenience and connection into everyday life.
When comparing costs, subtract expenses your parent would no longer have, including property taxes, homeowners insurance, maintenance, and certain utilities. This comparison can provide a clearer picture of the actual monthly difference.
Exploring Existing Assets Beyond Savings
Limited savings doesn't necessarily mean limited financial resources. Many older adults have assets that could help fund a move without relying entirely on monthly income.
Families may consider several possibilities:
- Home equity: Selling a house or renting it to generate income may help cover monthly expenses.
- Life insurance: Certain permanent policies have cash value that may be accessible through withdrawals, loans, or settlement arrangements.
- Personal property: Selling an unused vehicle, valuable collections, or other belongings can provide additional funds.
- Reverse mortgages: Eligible homeowners age 62 or older may access home equity while continuing to meet loan obligations and occupancy requirements.
Reverse mortgages generally require borrowers to maintain the home as their principal residence, making them unsuitable for many permanent moves into independent living.
Review potential tax consequences, transaction costs, and long-term implications with a qualified financial professional before making major decisions.
Exploring Family Contributions and Shared Expenses
Family contributions are another option when affording senior living on a fixed income becomes challenging. Adult children or other relatives may choose to share expenses, particularly when several family members can contribute smaller amounts.
Some families establish written agreements outlining monthly contributions and responsibilities. Others prefer flexible arrangements based on individual circumstances. Open communication helps everyone understand expectations and avoid financial misunderstandings.
Family members who cannot contribute financially may still assist with budgeting, paperwork, transportation, or coordinating the move. The goal is to develop an arrangement that remains manageable for everyone involved.
Discussing Independent Living Payment Plans and Community Options
Independent living payment plans and pricing arrangements vary by community. Rather than assuming a particular payment structure is available, ask about current rates, deposits, and any applicable promotions.
Some communities may offer flexible move-in arrangements or incentives, but these should always be confirmed before making financial commitments.
Conservatory at Champion Forest offers different apartment floor plans, allowing families to compare available accommodations and pricing with their financial options.
Questions to Ask About Monthly Costs
During your conversation with the community, clarify:
- Apartment pricing: How do monthly rates differ by floor plan?
- Included services: Which meals, housekeeping services, and amenities are covered?
- Additional expenses: Are transportation, guest meals, or optional services billed separately?
- Payment requirements: Are there community fees, deposits, or specific payment schedules?
Requesting a written breakdown makes it easier to compare options and identify a realistic monthly budget.
Understanding Senior Living Financial Assistance Options
Families researching senior living financial assistance options should understand that many public assistance programs have specific eligibility requirements.
Supplemental Security Income (SSI) may provide income to qualifying older adults with limited financial resources. However, it generally doesn't directly cover private independent living fees.
Veterans may qualify for certain VA benefits, depending on service history, financial circumstances, and eligibility requirements.
Local Area Agencies on Aging can also help families identify community resources and available assistance programs.
Medicare and Medicaid generally do not pay for the housing and lifestyle services associated with independent living.
Long-term care insurance typically covers qualifying personal assistance rather than independent living housing costs alone. Review individual policy terms before counting on reimbursement.
These distinctions matter when considering creative ways to fund senior living without assuming assistance will cover the full monthly expense.
Planning for Long-Term Financial Stability
Finding a way to cover initial expenses is only part of the process. Families should also consider whether their chosen arrangement will remain affordable over time.
A realistic financial plan should account for monthly income, available assets, anticipated rate increases, and unexpected expenses. Consider working with a financial advisor who understands senior housing expenses and long-term budgeting.
When exploring paying for independent living without money readily available in savings, combining several financial resources may provide a more sustainable solution than relying on one funding source.
Finding Affordable Independent Living Options in Spring, TX
Paying for independent living with limited savings requires comparing expenses, reviewing available assets, and exploring financial assistance carefully. Conservatory at Champion Forest offers a maintenance-free lifestyle with chef-prepared Sensations Dining, social opportunities through Celebrations, and convenient housekeeping services that may help simplify monthly budgeting.
Schedule a tour of Conservatory at Champion Forest to explore the Active Independent Living community, review current pricing, and discuss financial considerations with the community team.